
Key Takeaways:
- China’s government has set an ambitious goal for large-scale production of solid-state batteries by 2030, aiming to solidify its global leadership in electric vehicle (EV) technology.
- Despite this national directive, Contemporary Amperex Technology Co. Ltd. (CATL), the world’s largest EV battery manufacturer, warns that significant challenges remain in making the technology affordable and scalable for mass market adoption.
- While limited production of solid-state batteries may commence by 2027, industry experts believe that overcoming cost and manufacturing hurdles for widespread integration into millions of affordable EVs could extend well beyond the current decade.
- The roadmap highlights a comprehensive national strategy to advance battery innovation, encompassing various next-generation technologies beyond just solid-state.
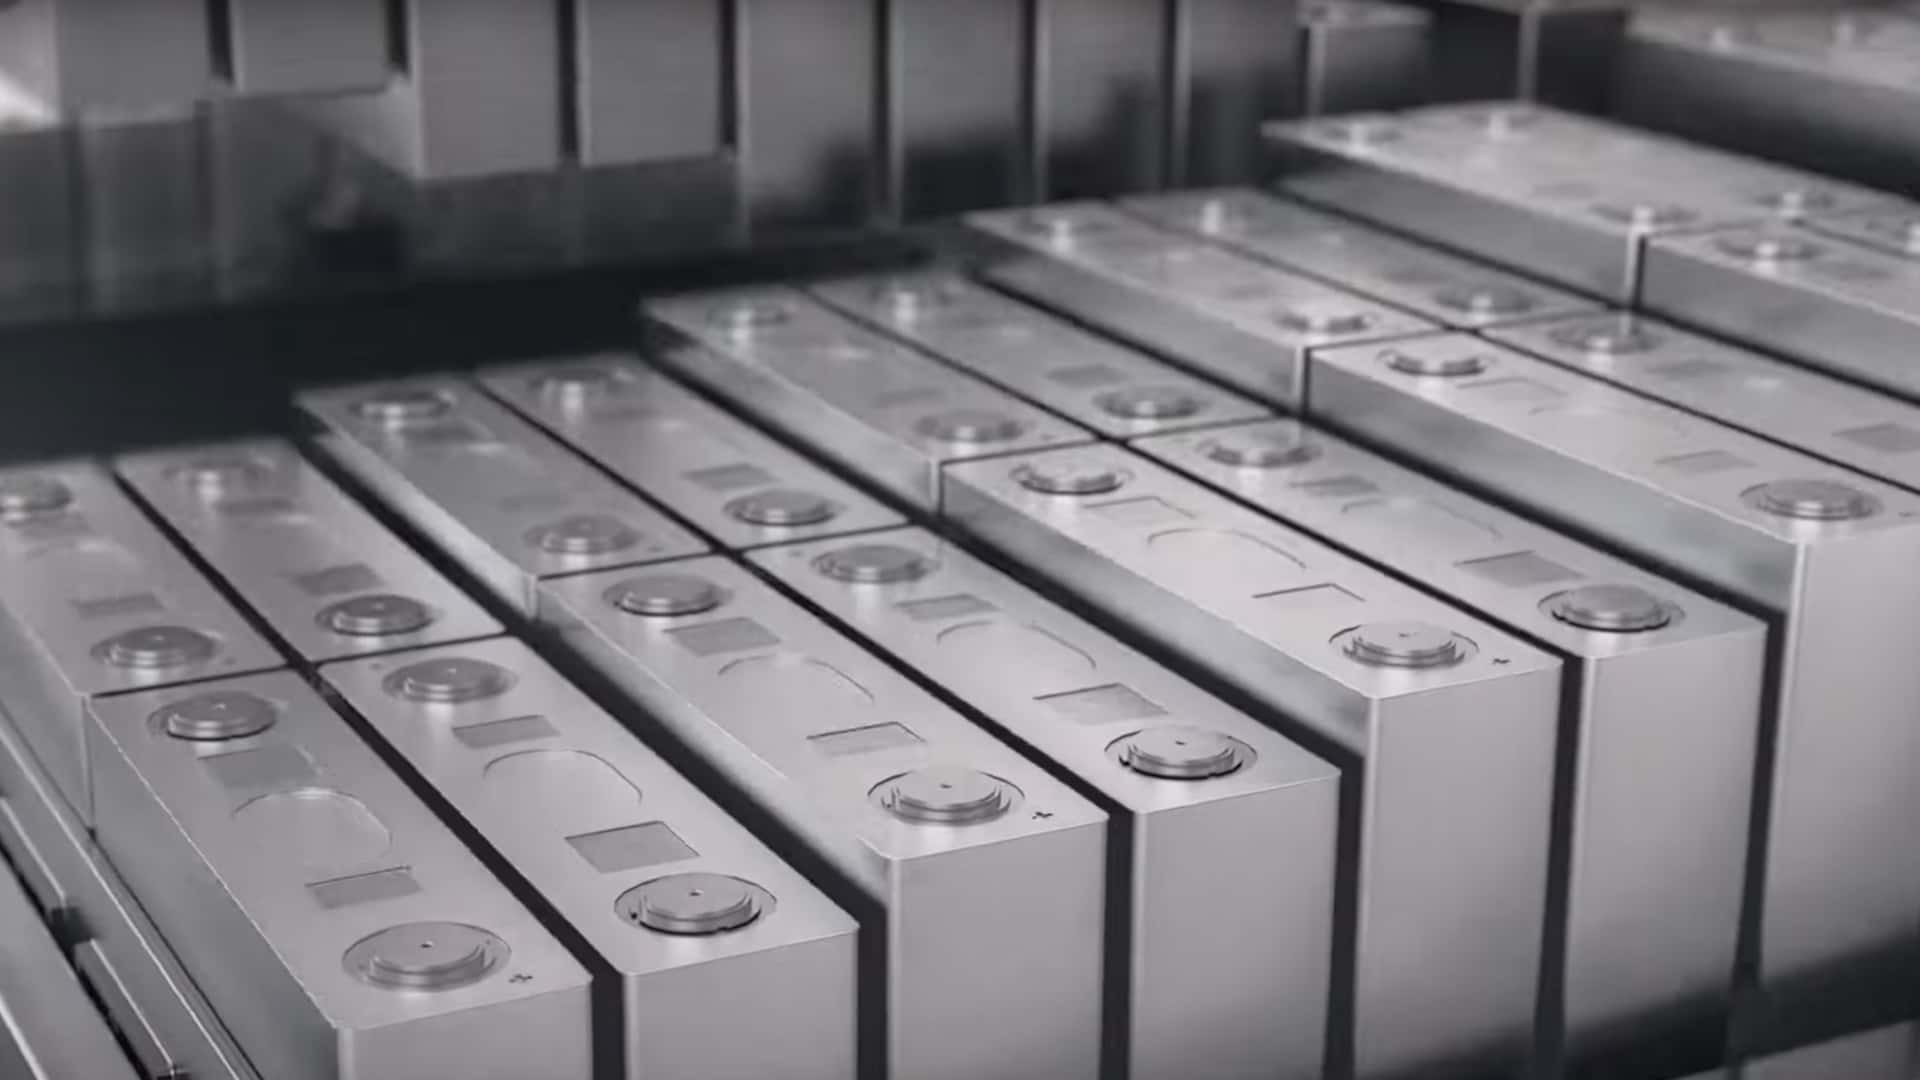
Beijing has declared a national objective to achieve large-scale deployment of solid-state batteries by 2030, a strategic move designed to extend China’s already commanding position in the global electric vehicle sector. This ambitious target was unveiled as part of a new, comprehensive battery industry roadmap on September 28.
While the prospect of advanced solid-state batteries powering the next generation of electric vehicles generates considerable excitement, industry leaders, including China’s own CATL, are tempering expectations with a dose of manufacturing and economic reality. The path from laboratory breakthroughs to mass market affordability is fraught with complex challenges.
Understanding the Solid-State Battery Promise
Solid-state batteries represent a significant leap forward from conventional lithium-ion batteries. They replace the flammable liquid electrolyte with a solid material, promising enhanced safety, higher energy density, and potentially faster charging times. These attributes are critical for longer-range EVs with improved performance and reduced risk.
The potential for these advanced battery solutions to transform electric vehicle technology is immense. Greater energy density translates directly into more compact battery packs and extended driving ranges, addressing key consumer concerns. Enhanced safety features could also pave the way for broader EV adoption.
Beijing’s Strategic Imperative
China’s drive for solid-state battery dominance is part of a broader national strategy to maintain its competitive edge in the rapidly evolving EV market. The country has meticulously built a robust battery manufacturing and research ecosystem, which it now seeks to leverage for next-generation technologies.
According to the South China Morning Post, this initiative aims to ensure China’s continued leadership in battery innovation, moving beyond its current strengths in traditional lithium-ion technologies. The government’s coordinated approach, often outlined in its influential five-year plans, provides a clear direction for both state-owned enterprises and private sector innovators.
The Ministry of Industry and Information Technology, while acknowledging the nation’s strong foundation, has also identified existing issues within China’s battery industry. These include acknowledged shortcomings in innovation capabilities and persistent imbalances between supply and demand, highlighting areas for targeted improvement.
CATL’s Pragmatic Outlook
Despite the national mandate, CATL, a global leader in battery manufacturing, has adopted a more cautious stance regarding the immediate widespread adoption of solid-state technology. Robin Zeng, CATL’s chairman, assessed the technology’s readiness at a modest level four out of nine on a readiness scale earlier this summer, with level nine indicating mass production viability.
Zeng articulated concerns about the performance and cost barriers that currently impede the technology. He suggested that widespread adoption in millions of vehicles is unlikely to occur before the end of the current decade. This perspective positions 2030 as a potential starting point for solid-state batteries to appear in more cars, rather than the year they become an industry-wide standard.
CATL has confirmed its plans to initiate limited production of solid-state batteries by 2027. However, the company has also indicated that scaling up to much larger volumes, necessary for true mass market penetration, will present substantial challenges.
The Technical and Economic Hurdles
The journey from laboratory concept to commercial viability for solid-state batteries is complex. Achieving lower costs, improving performance and stability, and making significant breakthroughs in materials science and manufacturing processes are critical prerequisites for large-scale deployment.
Industry experts outside China echo CATL’s caution. Robert Lee, North America president of LG Energy Solution, has specifically highlighted the inherent difficulties in manufacturing large solid-state cells. He, too, anticipates that the initial mass-market applications for this technology might not even be within electric vehicles, possibly emerging first in other energy storage solutions.
These warnings underscore the intricate engineering solutions required to transition from pilot projects to gigafactories. Scalability, material sourcing, and ensuring consistent quality across millions of units remain formidable obstacles for the entire battery industry.
Distinguishing Battery Technologies
It is important to differentiate between various stages of solid-state battery development. Semi-solid-state batteries, which retain some liquid electrolyte components, are already finding their way into a limited number of vehicles in China. However, these introductions should not be misinterpreted as an indication that all-solid-state batteries are ready for widespread adoption across the automotive sector.
Market analysts reflect this cautious optimism. BloombergNEF, for instance, projects that solid-state technology will account for a relatively modest 10% of the combined global demand for EV and battery-storage applications by 2035. This forecast highlights the long development and market penetration curve expected for these advanced battery systems.
Broader Vision for Battery Innovation
China’s recently unveiled battery roadmap is far-reaching, extending beyond just solid-state technology. It encompasses a diverse array of advanced battery solutions and performance targets.
The roadmap outlines national priorities that include the development of sodium-ion and flow batteries, both of which offer distinct advantages for specific applications, such as grid-scale energy storage. Furthermore, it emphasizes critical improvements in battery safety and temperature performance, vital for enhancing reliability and longevity in various climates.
Manufacturing quality is another key focus area, ensuring that China’s battery production maintains global standards. A separate, ambitious target calls for the development of long-life lithium batteries capable of enduring 15,000 charge cycles, although this specific goal does not necessarily imply that solid-state batteries will achieve a similar cycle life.
China’s Proven Industrial Blueprint
The coordinated national push for battery innovation should be viewed within the context of China’s highly effective industrial planning. The nation consistently sets its economic and industrial priorities through comprehensive five-year plans, which effectively align government agencies, research institutions, and businesses toward shared objectives.
The previous five-year cycle, spanning from 2021 to 2025, saw China significantly cement its dominance in the electric vehicle market. By the end of this period, the country was responsible for manufacturing an impressive 70% of global electric car production, demonstrating the efficacy of its strategic planning and substantial investments.
The new battery roadmap for 2026–2030 is meticulously designed to carry this established advantage into the next generation of battery technology. While bringing solid-state batteries into vehicles will undoubtedly be a significant milestone, the true measure of success will be their integration into millions of affordably priced electric cars, making advanced EV technology accessible to a broader consumer base.
The Path Ahead for Global EV Markets
As the global automotive industry increasingly pivots towards electrification, the race for superior battery technology is intensifying. China’s focused approach, backed by significant state support and a robust industrial base, positions it as a key player in this technological evolution.
The development and commercialization of solid-state batteries will not only influence the future of electric vehicles but also impact the broader energy storage landscape. The interplay between governmental ambition, private sector innovation, and fundamental scientific breakthroughs will determine the pace at which these transformative technologies reach global markets.
FAQ
What is China’s primary goal for solid-state batteries by 2030?
China aims for large-scale production and deployment of solid-state batteries by 2030. This initiative is designed to reinforce the country’s leading position in the electric vehicle (EV) technology sector and advance its capabilities in next-generation battery solutions.
Why is CATL cautious about the 2030 target for solid-state batteries?
CATL, a major battery manufacturer, expresses caution due to significant hurdles in achieving cost-effectiveness, performance stability, and manufacturing scalability for solid-state batteries. The company believes widespread adoption in millions of vehicles is unlikely before the decade’s end.
What are the main advantages of solid-state batteries for EVs?
Solid-state batteries promise enhanced safety by eliminating flammable liquid electrolytes, higher energy density for longer driving ranges, and potentially faster charging capabilities. These advancements are critical for improving EV performance and consumer appeal.
Are semi-solid-state batteries the same as all-solid-state batteries?
No, they are not the same. Semi-solid-state batteries incorporate some liquid electrolyte, making them an interim technology. All-solid-state batteries completely replace the liquid electrolyte with a solid material, representing a more advanced stage of development.
What other battery technologies are included in China’s roadmap?
Beyond solid-state batteries, China’s roadmap includes developing sodium-ion and flow batteries, improving battery safety and temperature performance, and enhancing manufacturing quality. It also targets long-life lithium batteries capable of 15,000 cycles.
How does China’s five-year plan system influence battery development?
China’s five-year plans provide a coordinated national strategy, aligning government, research, and industry towards specific economic and industrial goals. This structured approach helps accelerate technological development and manufacturing dominance, as seen in its current EV market share.
When might solid-state batteries become widely available in affordable EVs?
While limited production could begin by 2027, industry experts suggest that overcoming the cost and manufacturing challenges to integrate solid-state batteries into millions of reasonably priced EVs will likely extend well beyond 2030, marking a gradual market penetration.